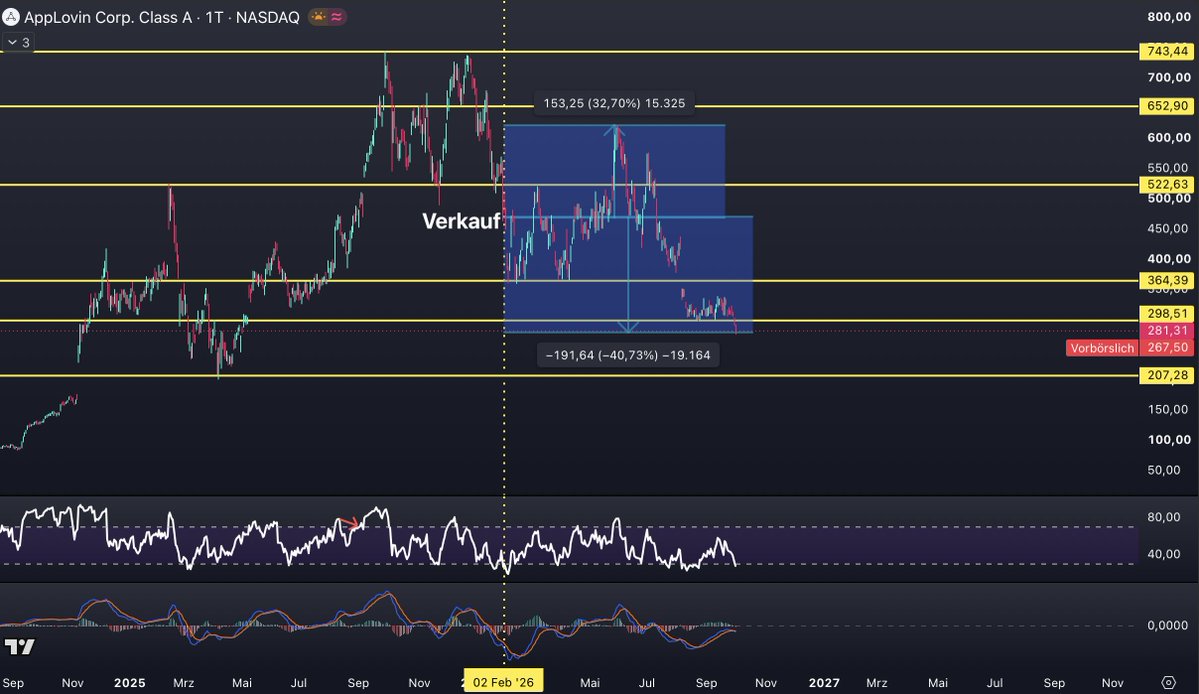
Maxim Röder wrote that he completely sold Applovin for a profit at the beginning of 2026. The stock then traded sideways for months and at times was significantly above his selling price, but is now around 41 percent below. The price trend shows him that evaluations of his decision changed depending on the stock's performance. For assessing Applovin, it is more important to understand the operational business and the valuation drivers, Röder wrote. The company has achieved a dominant position in mobile gaming with its AXON engine. Since the entire mobile gaming market is only growing organically in the low single-digit percentage range, gaming alone, in his opinion, can no longer enable sustainable hypergrowth rates. While the segment continues to generate high cash flows, it is not a sufficient growth driver for a hypergrowth valuation. The management is therefore trying to penetrate e-commerce and web advertising. However, this step is not proceeding linearly, Röder wrote. Outside of mobile gaming, Applovin lacks a natural moat; at the same time, training and computing costs are rising in the short term, and the market is skeptical. Analyst forecasts for medium-term revenue growth are already falling below 30 percent starting in 2027, he stated. Ultimately, it will be crucial whether the management is right with its e-commerce vision. #Aktienmarkt #Investieren #MobileGaming (translated)